

工业分销行业是制造和维护生态系统的关键但经常被忽视的支柱,其特点是利润微薄和竞争激烈。 Within this landscape, Global Industrial Company (GIC) has carved out a distinct position.与 W.W. GIC 拥有广阔的分支机构网络,或者拥有嵌入式现场服务的 Fastenal,GIC 运营着一种以电子商务、广泛的产品目录和价值驱动的自有品牌为中心的轻资本、数字化模式。 This strategic focus, rather than sheer scale, defines its economic profile and recent financial performance.
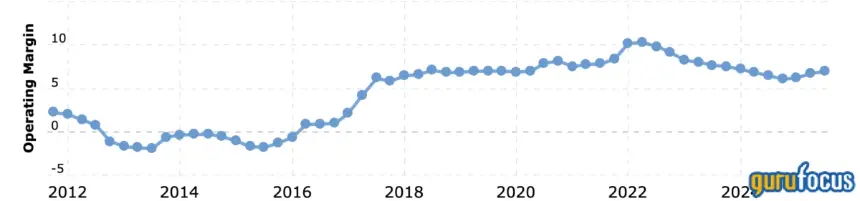
In its 2025 fiscal year, Global Industrial demonstrated the leverage inherent in its model.销售额增长 4.8%,达到 13.8 亿美元,但严格的执行使毛利率扩大了 120 个基点,达到 35.5%,营业收入猛增 21.2%,达到 9,760 万美元。这种营收增长和利润增长的脱钩凸显了企业的经济是由组合、效率和成本控制驱动的,而不仅仅是数量。
A key to understanding GIC's model is its hybrid fulfillment architecture.该公司在其八个集中配送中心储存速度更快、利润率更高的产品,同时利用代发货合作伙伴来销售流通速度较慢的产品。 This allows for a vast assortment without commensurate working capital burden.此外,其美国核心业务中超过 60% 的订单通过数字渠道(包括 EDI、打孔目录和 Ariba 等采购门户)流动,从而将公司嵌入客户的日常工作流程并减少摩擦。
Financially, the company generates robust returns on modest capital. Its Return on Invested Capital (ROIC) stands at approximately 20.7%, supported by low fixed asset intensity and a lean operating structure.自由现金流转换依然强劲,到 2025 年,该业务的销售额将达到 13.8 亿美元,产生约 7,470 万美元的自由现金流,利润率约为 5.4%。
然而,对现金转换周期 (CCC) 的表面分析揭示了一个潜在的担忧:它从 2020 年的约 38 天延长到 2025 年的约 64 天。更深入的研究澄清了这一趋势。 Accounts Receivable days have remained remarkably stable, moving only from 37.4 to 38.9 days over five years.整个 CCC 扩张归因于应付账款天数的压缩,应付账款天数从 2021 年的 69 天以上下降到 2025 年的 46.3 天。这表明该公司向供应商付款的速度更快,而不是客户付款的速度更慢,这是评估盈利质量和竞争地位的关键区别。
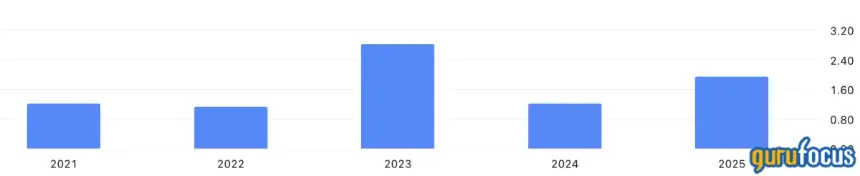
When benchmarked against peers, Global Industrial occupies a selective middle ground. Its gross margin of 35.5% is healthier than Applied Industrial's (30.3%) though below leaders like Fastenal (45.0%).其营业利润率 (7.1%) 和自由现金流利润率 (5.4%) 低于该行业表现最好的企业,但其资本足迹明显减少,这解释了其稳健的投资回报率。
The market's valuation of GIC appears pragmatic, pricing it as a steady operator rather than a high-growth compounder.该公司的市盈率约为 17 倍,EV/EBIT 约为 12 倍,股息收益率高于 3%,较 Grainger(市盈率约为 31 倍)和 Fastenal(市盈率约为 42 倍)等规模较大的同行存在折扣。机构所有权是分散的,这对于被视为多元化投资组合中可靠的现金流发生器而不是高度确信的、必须拥有的资产的股票来说是典型的情况。
The long-term investment thesis hinges on this potential mispricing. The market seems to apply a discount for GIC's smaller scale while conflating the payables-driven CCC expansion with weaker business quality.如果 AP 日稳定在当前水平附近,并且公司继续通过自有品牌渗透和数字效率来提高利润率,那么相对于其基本经济因素(干净的应收账款、提高的盈利能力和强劲的现金生成)的估值差距可能会缩小。核心风险仍然是供应商付款条件是否已经找到底线,或者进一步压缩是否会对历史上定义业务的资本效率模型造成压力。